Image 01 Image 03

Economy Tag

Remember when Obama and all of his allies in politics and media told us that the Affordable Care Act would save money for working families and the country? It turns out that promise was as good as the one about keeping your doctor. The truth is that the cost of Obamacare is going up pretty much everywhere. Daniel Bassali reports at the Washington Free Beacon:
Our National Obamacare Nightmare Despite enjoying a victory in the Supreme Court this summer, the Affordable Care Act, President Barack Obama’s signature domestic law, has suffered through a year of bad news. While the administration has touted that nearly 12 million people have gained access to health care insurance, premiums for most Americans are expected to increase in 2016. Insurance companies are seeking rate increases between 20 and 40 percent.
Art Laffer, famed member of President Reagan's Economic Policy Advisory Board, has co-authored, with Stephen Moore, an article for Investor's Business Daily in which they assert that Rand Paul and Ted Cruz have the "best" tax proposals. They begin with a bit of a warning to those serious about tax reform:
All the GOP tax plans look good to us — though some are admittedly better than others. The danger now is that too many conservatives have formed a circular firing squad and are shooting down nearly all proposals on purity grounds or attacking trivial differences. This is the surest way to derail tax reform altogether. If Ronald Reagan, Jack Kemp and Bill Bradley had held to such a "my way or the highway" approach, the epic 1986 tax reform that collapsed tax rates to 15% and 28% never would have happened.
That said, Laffer and Moore continue by narrowing their focus to Rand and Cruz:
Which brings us to Rand Paul and Ted Cruz. The two of us helped craft their low-rate flat tax plans. The plans are similar: Paul's rates are 14.5% on business net sales and wages and salaries. Cruz has a 16% business net sales tax and a 10% wage and salary tax.

President Obama's approval ratings may be circling the drain, but a new Gallup poll released today shows that they're slightly less terrible than usual. Small miracles? American approval of Obama's handling of health care and the economy just clocked in at 44%, which represents a three-year high in both categories. The last time Obama did this well in the polls, he had just been elected to his second term; back then, an anemic 44% still represented a significant boost over the President's first term numbers. Gallup explains the trend:
Americans have not been as approving of Obama's performance on the economy since November 2012, just after the president was re-elected to a second term. The 44% he received then was similar to the 45% right before Election Day. Both scores were major improvements from the sub-40% ratings he'd received during much of his first term -- including a record low of 26% in August 2011 after contentious negotiations with Congress to raise the debt limit. Obama's best marks on the economy -- between 55% and 59% -- came during his first few months in office. Over the past three years, Obama's economic approval rating has fluctuated, reaching a low of 33% in 2014.

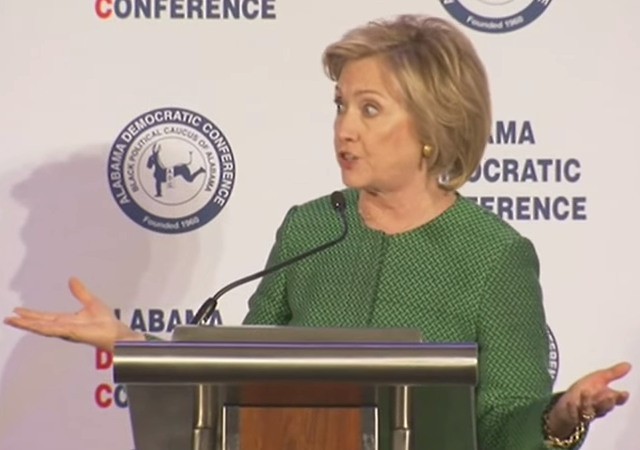
Hillary Clinton visited Alabama this weekend and while nearly all of the early media reports are about her absurd claim that Republicans are trying to disenfranchise black voters, it was her remarks about the economy that were truly stunning. In the Associated Press video below, Hillary suggests that it is always Republican presidents who create financial messes which have to then be cleaned up by Democrats. She touts the financial record of her husband before accusing Bush of leaving Obama with a massive debt. She goes on to praise Obama and claim that he never gets enough credit. Clinton conveniently leaves out the role Democrats played in the 2008 financial crisis when they forced banks to give home loans to unqualified borrowers. She also neglects to mention the massive debt accumulated by Obama.

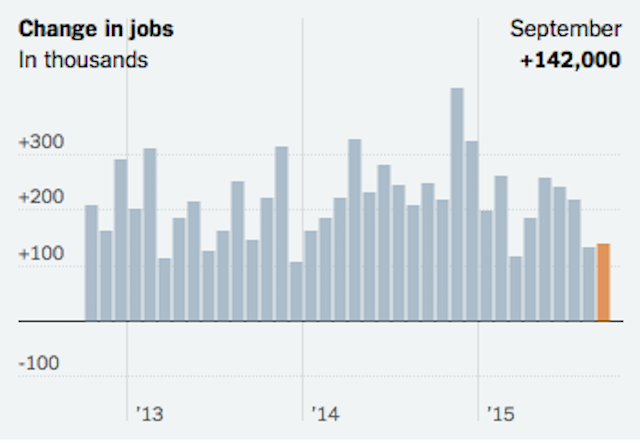
The latest jobs report released today could spell trouble for the US economy---and workers. According to analysts, the economy underperformed in terms of jobs created. Experts surveyed by CNNMoney estimated that we would see a net gain of 204,000 jobs in this report; gains in excess of 200,000 are considered "healthy," so this was an optimistic prediction. In reality, however, the economy only added 142,000 jobs in September---an "unhealthy" diagnosis. The unemployment held steady at 5.1%; however, labor force participation rate dropped to 62.4 percent (from 62.6 percent), and the three month average for job creation has stagnated well below 200,000. More via the NY Times:
Friday’s report came just two weeks after the Federal Reserve decided that the recovery was still too frail to risk lifting interest rates from their near-zero level. The latest evidence of a weakening economy may push any rate increase into next year even though the Fed chairwoman, Janet L. Yellen, had previously suggested that the central bank was likely to go ahead with a rate increase before year’s end.

Is this the wave of the future?:
Central bank policymakers had believed they had run out of room to support their respective economies, with their interest rates held close to the floor. ...Cut rates too deeply, [they thought], and savers would end up facing negative returns. In that case, this could encourage people to take their savings out of the bank and hoard them in cash... [But as] central bank rates have turned negative, the rates offered on bank deposits have followed. Yet rather than stuffing cash under mattresses, people have left their money in the bank or spent it.
This is already happening in Sweden. One of my first thoughts on reading that people are not pulling their money out of the banks was that perhaps the Swedes are just used to the habit of banking and don't quite know where else to put their money. After all, a few hundred thousand kronor would be hard to stuff under a mattress, and perhaps anxiety-provoking. And it is true that Sweden already has a very high savings rate.

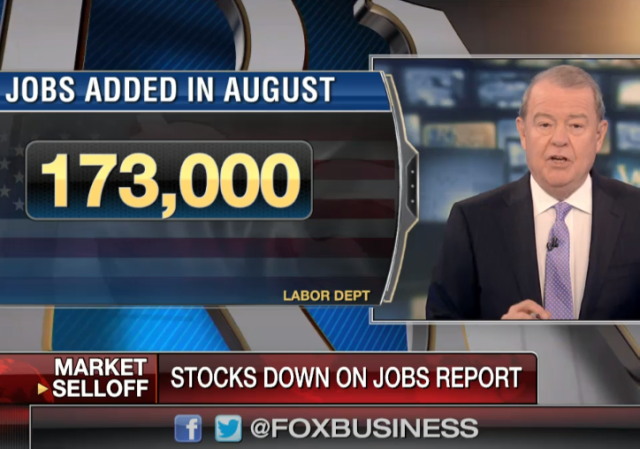
Democrats are probably very happy with the August jobs report and the new unemployment rate of 5.1, but if you look closely at the issue, there's no reason for turning cartwheels just yet. Susan Jones of CNS News:
Record 94,031,000 Americans Not in Labor Force; Participation Rate Stuck at 38-Year Low for 3rd Straight Month A record 94,031,000 Americans were not in the American labor force last month -- 261,000 more than July -- and the labor force participation rate stayed stuck at 62.6 percent, a 38-year low, for a third straight month in August, the Labor Department reported on Friday, as the nation heads into the Labor Day weekend. The number of Americans not in the labor force has continued to rise, partly because of retiring baby-boomers and fewer workers entering the workforce. In August, according to BLS, the nation’s civilian noninstitutional population, consisting of all people 16 or older who were not in the military or an institution, reached 251,096,000. Of those, 157,065,000 participated in the labor force by either holding a job or actively seeking one.

Greece's wild ride through the wake of the Eurozone mega-bailout continued to bounce along today as far-left lawmakers split off from the (already far-left) Syriza party to form their own rebel faction. Former energy minister Panagiotis Lafazanis and his fellow malcontents now have three days to bolster the new Popular Unity party and cobble together a coalition government. (Previous efforts to seize control by Syriza's main opponent, the conservative New Democracy party, failed.) Lafazanis has no grand illusions about being able to do so, which means that Greek voters will head to the polls as early as September 20 to elect new representatives. The early election cycle snapped into place after embattled Greek Prime Minister Alexis Tsipras resigned last week amid harsh criticism from his colleagues over the terms of the multibillion dollar bailout. More from the New York Times:
"Some people think they can hide the consequences of the (bailout agreements) from the Greek people," Lafazanis said, commenting on Tsipras' decision to trigger elections, as he met with President Prokopis Pavlopoulos to receive the mandate to form a government. "This is democratic backtracking, if not an undemocratic aberration."

Late last month, Illinois Governor Bruce Rauner (R-eal Life Republican) made headlines after he allowed his government to go into a partial shutdown rather than succumb to Democrats' demands for a tax-and-spend budget. Now, almost a month later, democrats are still pushing for more taxes and more entitlement spending---but Rauner isn't backing down. At the forefront of the assault against Rauner's efforts to curb Illinois' $6 billion dollar deficit (the largest in the nation) are the state's infamous unions. AFSCME's (the state, local, and municipal workers' union) contract ran out with the State of Illinois on June 30, and officials are warning Rauner that if he refuses to deal, union members will go on strike. Back in May, Illinois' Democrat-controlled legislature passed a bill that would bring in an arbitrator if either the State or the union declares an impasse in contract talks; Rauner, however, is expected to veto that bill, which means that a union strike could be in the cards. For their part, Rauner's administration seems to be preparing for much worse than a slowdown. According to a report by the State Journal-Register, staffers have been contacting retired state employees and floating the idea of short-term contract work in the event that the union decides to strike.

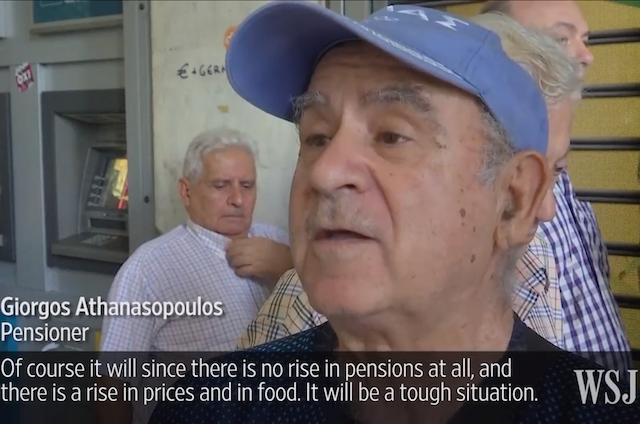
For the first time in three weeks, Greek banks opened for business; but for account holders, that renewed access to cash comes at a price. Although doors opened and ATMs were stocked, Greeks looking to cash out were met with the continuation of withdrawal restrictions of 60 euros per day; the government slightly relaxed the rules put in place during its negotiations with the rest of the Eurozone, and set an additional 420 euro per week limit, eliminating the need for daily runs on ATM machines and bank tills. Checking transactions are limited to deposits, and account holders are still restricted from taking out cash while abroad. Shoppers saw a 10% hike in the country's VAT tax approved by parliament on Thursday; parliament also agreed to reforms of pension and early retirement programs that have Greek citizens worried. The Wall Street Journal has on the ground coverage: Of course, those worrisome cuts were demanded by creditors for very good reasons.

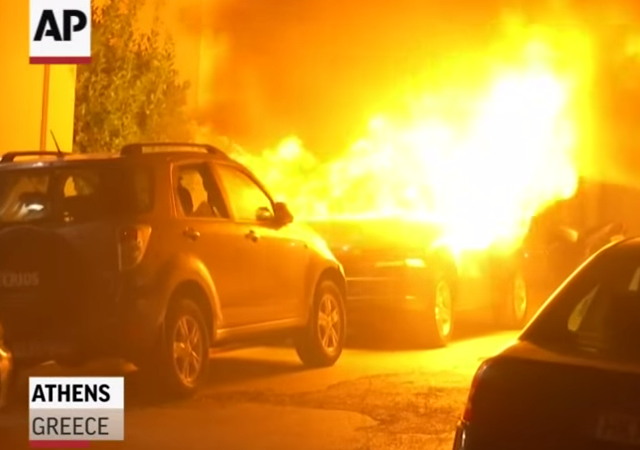
After a full month of drama, Greece and its creditors finally agreed on a multi-billion dollar bailout package. One of the bailout's most controversial conditions is a list of new austerity measures, and we all know how many Greeks feel about those. Anti-austerity violence broke out on the streets of Athens last night. Megan Specia of Mashable reported:
Tensions were high on Wednesday night outside the Greek parliament building on Athens' Syntagma Square, which was the center of violent anti-austerity protests in years past. And while the streets of Athens were largely calm for much of the day, despite thousands marching against austerity measures tied to the country's new bailout agreement, the night took a more violent turn. As night fell, clashes broke out between protesters waiting to hear the fate of their country's economic future and the police sent to keep them calm.

After 22 hours of fierce negotiating, the Eurozone summit has come up with a deal that will keep Greece in the Eurozone in exchange for both budget cuts and tax hikes. For those who oppose austerity and "euro"centric economics, the deal is a huge blow. Europe has agreed to advance Greece 10 billion Euros to help the flailing country pay down it's 3.5 billion euro debt to the IMF. Greece will also receive around 77 billion dollars in aid over three years in part to help strengthen it's banking system. European officials will also review Greece's total debt, but will not (!) reduce the amount to be paid back. In return, Greek officials have agreed to a line of policy changes that include cuts to pensions and an increase in the sales tax, with the goal of increasing the budget surplus. They must also make steps to privatize much of the economy, which will (hopefully) increase competition in local markets, and contribute 50 billion euros worth of privatized assets into a fund that will be used to help Greece pay off its debt. In short, it's an activist's worst nightmare. More via the Wall Street Journal:

Things are bad in both of China's big exchanges; both the Shanghai and Shenzen are seeing companies halting their trading on both:
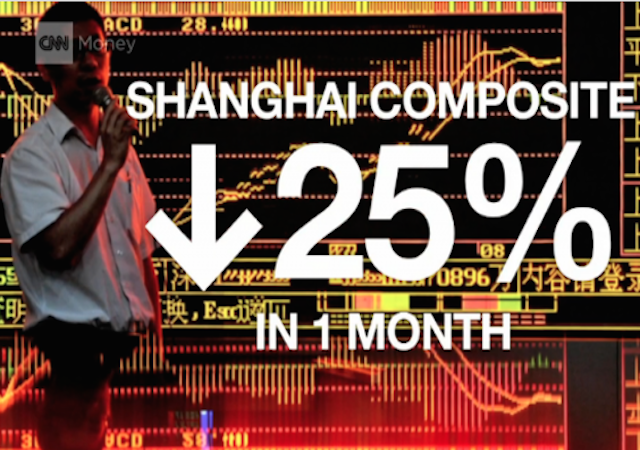
Over 700 Chinese companies have halted trading to "self preserve," according to the state media. That means about a quarter of the companies listed on China's two big exchanges -- the Shanghai and Shenzhen -- are no longer trading. China's stock markets are in trouble. The Shanghai Composite Index has fallen over 25% since mid-June. The Shenzhen, which has more tech companies and is often compared to America's Nasdaq Index, is down even more.
Government intervention has not helped:
Chinese stocks fell on Tuesday, taking little comfort from a slew of support measures unleashed by Beijing in recent days, and unnerved by Chinese Premier Li Keqiang's failure to mention the market chaos in a statement on the economy. Before the market opened, Li said in comments posted on a government website that China had the confidence and ability to deal with challenges faced by its economy, but had nothing to say on the three-week plunge that has knocked around 30 percent off Chinese shares since mid-June.
Morgan Stanley Asia Chairman Stephen Roach said some of China's problems can be traced back to issues related to the debt-to-GDP ratio:

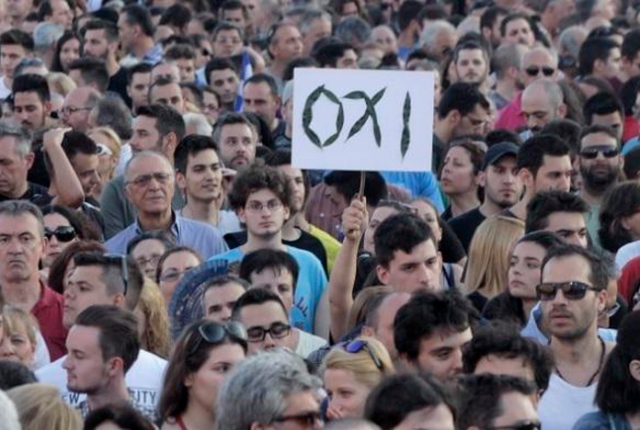
US stock prices sank into the negative this morning in the wake of Greece's landslide "no" vote rejecting a referendum that would have created yet a new layer in the flailing country's creditor-debtor relationship with more stable Eurozone countries. In the US, the Dow showed a mid-morning flatline, but recovered by the afternoon. Markets in Asia, however, experienced a more dramatic response, and Japan and South Korea both closed under significant decline. The response of the European market was more modest, but still reflected uncertainty as Greece pushes its creditors for a mercy ruling. More via USA Today:
"There's been no panic of any kind," Paul Hickey, co-founder of Bespoke Investment Group told clients. "The market remains faithful that the European Central Bank and other European institutions have done an adequate job firewalling the eurozone against Greece." Investors, at least so far, are behaving as if they do not fear financial contagion from the Greek crisis, unlike the financial infection that spread globally after Wall Street bank Lehman Brothers filed for bankruptcy back in the fall of 2008. "The week ahead will be dominated by Greece and the implications of the landslide 'No' vote," says David Kelly, chief global strategist at JPMorgan Funds, adding that he expects difficult negotiations ahead between the two parties.

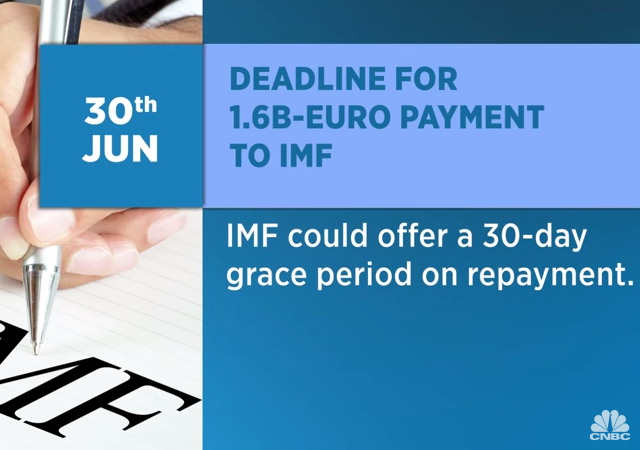
What was once considered unthinkable has now happened. Having missed the June 30th deadline for payment on its debt, the country of Greece has effectively defaulted. This is going to have a considerable effect on the economy of the European Union, which Greece might now leave. It's likely that this situation will get worse before it gets better. First, the basic facts. Michael Birnbaum of the Washington Post:
Greece fails to make key IMF debt payment Greece lost its financial lifelines Tuesday, as the country missed a crucial payment to the International Monetary Fund amid growing questions about whether it would be able to remain in the euro zone. Greek leaders had made a last-ditch attempt to come up with the necessary cash, asking European countries for a new bailout hours before its last ones were set to expire, but E.U. finance ministers rejected the request as unrealistic. The missed payment, confirmed by the IMF, was a landmark moment in Europe’s five-year battle to preserve its common currency. The E.U. finance chiefs were set to reconvene Wednesday as Greece’s cash dwindles and its banks remain closed. The ministers’ decision to hold firm was a sign that they believed they had successfully put in place the defenses­ against instability in Europe if a country left the euro zone. But as Greece became the first developed nation to miss a payment to the IMF, E.U. leaders were confronting the prospect of a European country plunging into intense financial misery as it was forced to abandon the currency.
In the coming days, you're going to hear some quibbling about whether or not this was a default.

Illinois' new budget year starts tomorrow, and unless Republicans and Democrats can come to an agreement on fiscal policy, the state will kick things off without the ability to pay the bills. Illinois has a reputation for being largely rural, yet bafflingly Democratic. The Chicago machine---not those languishing in my old stomping grounds in the capitol of Springfield---runs things, but for the first time in over a decade, a solidly Democratic legislature is dealing with a Republican governor. Bruce Rauner has spent his time bucking the trends that have run Illinois into the ground, but Democrats have, in turn, bucked his pro-business agenda and are demanding a massive tax increase to make up for a $4 billion dollar shortfall. The AP has the back story:
The back-and-forth is the latest in a months-long fight between Rauner and majority Democrats over how to resolve Illinois' massive financial problems and — more recently — who will take the blame if state government begins grinding to a halt and critical services are cut off. The two sides have been deadlocked over how to eliminate a deficit that's the largest of any state in the U.S. Illinois already is billions behind in paying its bills and has the nation's worst-funded state pensions, with a more than $100 billion shortfall.

Greece and the Eurozone have been unable to reach an agreement ahead of a bailout deadline which quickly approaches on June 30th. If negotiations fail, Greece could leave the European Union and ultimately face economic collapse. The situation is already causing a dash for cash in the debt strapped country. Bloomberg reports:
Greeks Line Up at Banks and Drain ATMs as Tsipras Calls Vote Some Greek banks were beginning to limit cash transactions as hundreds of people lined up outside branches and drained cash machines after Prime Minister Alexis Tsipras called a referendum that could decide his country’s fate in the euro. Two senior Greek retail bank executives said as many as 500 of the country’s more than 7,000 ATMs had run out of cash as of Saturday morning, and that some lenders may not be able to open on Monday unless there was an emergency liquidity injection from the Bank of Greece. A central bank spokesman said it was making efforts to supply money to the system.

The new left-wing leaders in Greece have done little to stem the country's growing financial crisis and even members of the Obama administration are now urging them to act. NBC News reports:
Greece Debt Crisis: U.S. Warns Athens to Reach Deal or Face 'Decline' ATHENS, Greece — The United States turned up the heat on the Greek government over its debt crisis Saturday, urging it to reach a deal with creditors as wearied citizens braced for a national default. Treasury Secretary Jack Lew said in an interview that the government in Athens should make tough fiscal decisions or risk devastating both the country's economy and people. "I think we're at a moment now where the burden is on Greece to come back with a response that's the basis for reaching an agreement as quickly as possible," he said in an episode of CNN's "Fareed Zakaria GPS" program that will air on Sunday, according to a transcript provided to Reuters. "It's clear that within Greece, the consequence of a failure here would mean a terrible, terrible decline in their economic performance," he said. "It will hurt the Greek people. They will bear the first brunt of a failure here."